EveryDollar: Budget Management

- 6.57K Reviews
- 4.3
- Downloads
- 1,000,000+
 Analysis by Mobxio
My first useful moment with EveryDollar wasn’t building a perfect budget; it was seeing the month’s income divided into clear choices before I spent it. That shift is the app’s main appeal. Rather than treating a budget as a report card you check after the money is gone, I found it works best as a plan you revisit as bills and everyday purchases happen. If you’re new to budgeting, that can make the first step feel manageable: start with what comes in, give it jobs, and adjust when real life refuses to follow the plan.
What to expect from a hands-on budget
EveryDollar is a finance app from Ramsey Solutions built around intentional expense planning. Its store summary points to managing bills and tailoring an expense report to understand spending and save money; in practice, the useful habit is making a plan and then keeping it current. The app is free to download, with optional in-app purchases ranging from $7.99 to $129.99 per item. It has an average rating of 4.3 from around 15,000 ratings, and more than 1 million installs. Those figures suggest a well-used budgeting tool, but they don’t guarantee that its approach will suit everyone.
The app is rated for Everyone, was released on July 10, 2016, and its current version is 2025.11.260, with Android 8.0 as the minimum operating system. I’d think of it less as a passive tracker and more as a routine: you decide the categories and amounts, then record spending against them. That distinction matters if you’re used to a banking app that simply shows transactions after they clear.
For a first-time user, that hands-on approach is both the attraction and the commitment. You don’t need to begin with a sophisticated financial plan. A simple first pass—income, regular bills, food, transport, and a little room for irregular costs—is enough to make the budget informative. I’d resist the urge to make dozens of tiny categories on day one. If a category is hard to understand or maintain, it is unlikely to help you make a better decision at the checkout.
Building a budget you can actually use
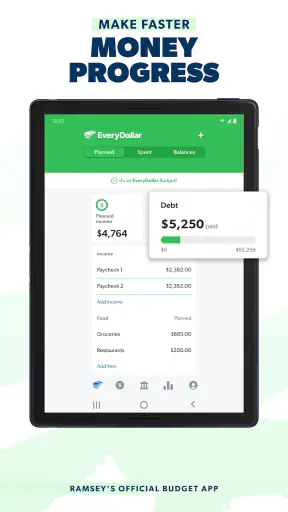
Getting started with EveryDollar is a breeze. You just download the app, set up your account, and you’re off to the races. The app asks you to input your income and then guides you through setting up your budget categories. It’s like having a financial coach in your pocket, helping you decide how much to allocate for groceries, entertainment, and those pesky bills.
First setup: begin with the bills you know
I’d start setup with predictable commitments rather than trying to remember every purchase you’ve ever made. Add the bills that recur, then give practical estimates to flexible areas such as groceries or transportation. If your pay varies, use a cautious figure you can reasonably plan around instead of building the whole month on an unusually good paycheck. That makes the first version less exciting, perhaps, but much more useful when the month gets tight.
Next, leave room for expenses that are real but don’t arrive every month. Car maintenance, annual renewals, school costs, and seasonal needs can make a budget look wrong if they have nowhere to go. Even if you can’t predict the exact amount, a category or a small planned allowance helps reveal that these costs are part of normal life, not sudden failures. This is one of the most useful habits to develop early: a budget should reflect the calendar you live with, not only the bills due this week.
More Stories to Explore
Uber Eats After the OS Update: Better Tracking, More Permission Friction
Google Chrome Wins App of the Week for Making Everyday Browsing Easier
Wordscapes Makes the Five-Minute Break Feel Complete
Switching to Audible Means Building a Listening Habit
Moovit Review: A Better Transit Guide When Your City Has the Data
Brave’s Privacy Has Limits Set by Android and iOS
User-Friendly Interface
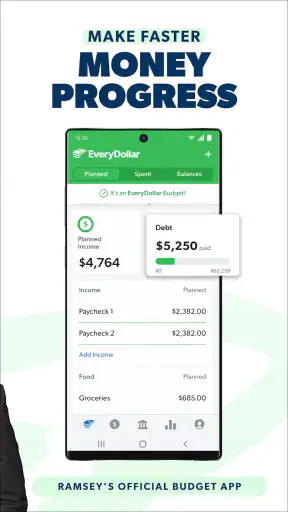
The interface is as smooth as butter. Seriously, it’s got this clean, intuitive design that makes the whole budgeting process feel less daunting. The navigation is straightforward, which means you won’t find yourself lost in a sea of tabs and options. You can easily see where your money is going, which is kind of the whole point, right?
Still, a simple layout can’t decide your priorities for you. When you’re choosing categories, the hardest part may be agreeing on what counts as essential, especially if you share expenses with a partner or family. I’d keep names plain and categories broad enough that you can remember them without checking a guide. If you find yourself debating whether a small purchase belongs in one of several nearly identical categories, combine them and make the habit easier to sustain.
First successful action: log one purchase
Once the plan is in place, the quickest way to make it feel real is to enter an expense immediately after paying. The original appeal of manual tracking is that it puts the choice in front of you while you still remember it. For example, after a grocery run, record the total under groceries and compare what remains with the week’s needs. That simple check can help you decide whether to use what’s already at home for dinner or make another stop at the store.
One of my favorite features is the ability to track expenses in real-time. Just whip out your phone at the checkout counter, input the amount, and boom—your budget is updated. It’s super satisfying to see everything in neat little categories, and it really makes you think twice about that extra latte.
My practical tip is to enter purchases at a moment you already have your phone out, such as after paying or while waiting for a receipt. Leaving a pile of entries for the end of the week makes it easier to forget cash purchases or misremember which category fits. If you’re not ready to log every small transaction, begin with the spending areas where you most often lose track. A consistent record of a few important categories can teach you more than an ambitious plan you abandon.
Common confusion: a plan is not the same as a bank feed
Manual entry asks for attention, and that’s not a flaw so much as a trade-off. It can make spending more conscious, but it also means the budget is only as current as the entries you make. If you rarely open a finance app or expect every purchase to appear automatically, the free approach may feel like work. The premium version offers direct bank-account connections and transaction syncing, which can reduce the need to enter each expense yourself. Optional purchases are listed at $7.99 to $129.99 per item, so check the in-app terms and available options before deciding whether that convenience is worth paying for.
There’s also a difference between seeing a transaction and planning for it. A bank app may be better at showing balances and posted activity, while EveryDollar’s budgeting method asks you to decide in advance how money should be used. If you connect accounts, I would still review the categories rather than assume every transaction has been placed exactly where you want it. Automatic syncing can save entry time, but it doesn’t replace your judgement about whether a purchase was necessary or whether a category needs adjusting.
Making room for goals without overpromising
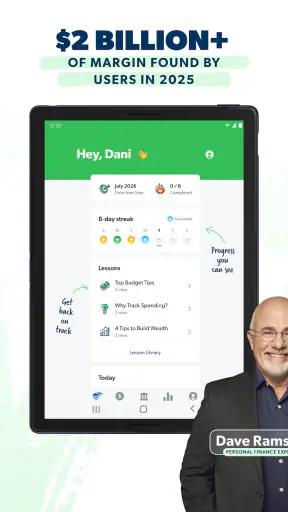
What’s awesome about EveryDollar is its focus on goal setting. Whether you’re saving for a vacation, a new gadget, or just trying to build an emergency fund, the app helps you set and track your progress. Watching that little progress bar fill up is oddly satisfying and definitely keeps you motivated.
A goal becomes more useful when it is connected to a repeatable choice. If you want to build an emergency cushion, decide what amount you can set aside without making essential bills uncertain, then check the plan when income or expenses change. I wouldn’t treat a progress display as proof that a goal is affordable; it is a prompt to keep your choices visible. If the month becomes unusually expensive, revise the plan rather than quietly relying on money that has another job.
This approach is especially helpful for someone saving toward a near-term purchase who tends to spend whatever is left in an account. It may be less satisfying for a person who wants investment analysis, credit monitoring, or a detailed view of net worth. EveryDollar’s strength is the day-to-day allocation of income, not serving as an all-purpose financial dashboard. If those broader tools are your priority, a banking or personal-finance service built around them may be a better fit.
Everyday trade-offs and who benefits most
Imagine getting paid, paying the rent and utilities, and then realizing that a few casual lunches have used the money you meant to keep for groceries. With a current budget, you can check the food category before deciding what to spend. If the balance is low, that does not automatically mean you have failed; it tells you to adjust a choice, move money deliberately if appropriate, or plan a simpler week. The value is in noticing early enough to respond instead of discovering the shortfall after several unrelated purchases.
I think the app is a good match for people who want a clear monthly plan, are willing to check it regularly, and prefer assigning income to categories over reviewing charts after the fact. It can also help couples or housemates discuss shared spending, provided they agree on the categories and keep entries current. It is not the best choice if you want budgeting to happen entirely in the background, dislike manual upkeep, or need complex tools for several accounts and financial goals. A spreadsheet may suit someone who wants total flexibility; a bank’s built-in tracker may be easier for someone who only wants to review transactions without making a detailed plan.
The balance between simplicity and detail is worth testing rather than guessing. Too few categories can hide a spending problem; too many can turn logging into a chore. I’d begin with the large, decision-making areas and split a category only when the distinction would change what you do. For example, separating essentials from optional treats can be more actionable than tracking every type of snack individually. This keeps the budget readable when you need a quick answer.
Connectivity and Syncing
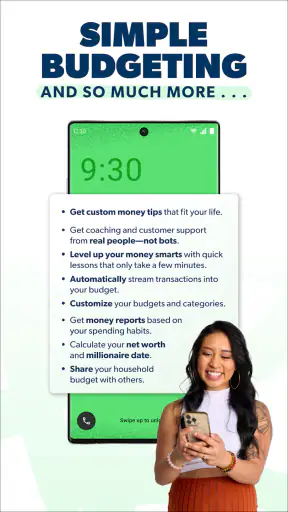
The app offers a premium version that allows you to connect directly to your bank accounts. This feature is a game-changer for those who don’t want to manually input every expense. It automatically syncs your transactions, so you’ll always be in the loop about where your money is going.
The free version still packs a punch, allowing you to manage your budget effectively without paying extra. It’s a sensible way to see whether you like the method before considering a paid option. I’d use the first few weeks to notice how often you actually miss manual entry and whether syncing would solve that specific problem. If you are comfortable recording purchases yourself, paying for automation may not improve the decisions you make. If the task is the main reason you stop budgeting, the convenience could matter more.
Before changing how you track, consider your own comfort with connecting financial accounts and the effort you are trying to remove. Some people prefer manual entry because it keeps every purchase visible to them; others would rather spend their time reviewing the plan than typing amounts. Neither preference is automatically better. The right choice is the one that lets you keep the budget accurate without making money management feel like a second job.
Keeping the routine realistic
A useful routine does not need to be elaborate. I’d check the budget when income arrives, update expenses in small batches, and take a short look before making a discretionary purchase that could affect the rest of the week. Then, near the end of the month, I’d note which estimates were consistently off and adjust those categories for the next plan. This turns budgeting into a learning loop rather than a demand to get every number right on the first try.
When something unexpected happens, avoid changing several categories at once just to make the plan look tidy. First identify what changed—income, a bill, or a one-off expense—then decide which flexible area can realistically absorb it. That small pause is where a budget can be more helpful than a transaction list: it gives you a chance to choose what gets protected and what can wait.
However, the free version still packs a punch, allowing you to manage your budget effectively without shelling out extra cash. It’s perfect for those who are just dipping their toes into the world of budgeting.
Final Thoughts
In a world where financial peace seems like a distant dream, EveryDollar offers a practical solution to get your finances in order. It’s user-friendly, motivating, and most importantly, effective. If you're looking to take control of your finances and make every dollar count, this app might just be your new best friend.
So go on, give it a shot, and watch how your financial habits transform. Trust me, your wallet will thank you.
EveryDollar: Budget Management FAQ
What is EveryDollar and how does it help with budgeting?
EveryDollar is a budgeting app designed to help users manage their finances effectively. It allows you to create a monthly budget, track your spending, and ensure every dollar is accounted for. With user-friendly features, it simplifies financial management and helps you stay on top of your financial goals.
Is EveryDollar free to use, or are there any costs involved?
EveryDollar offers both a free version and a paid premium version called EveryDollar Plus. The free version provides basic budgeting tools, while the premium version offers additional features like automatic bank transactions and priority support. Users can choose based on their budgeting needs and preferences.
How secure is my financial information with EveryDollar?
EveryDollar prioritizes the security of your financial data by using bank-level encryption and secure data storage. Additionally, the app does not store your bank login credentials. Users can feel confident that their personal and financial information is protected when using EveryDollar.
Can EveryDollar be used across multiple devices?
Yes, EveryDollar is accessible on multiple devices, including smartphones, tablets, and desktops. This cross-platform functionality allows you to manage your budget on-the-go and syncs your data in real-time, ensuring you have the latest updates no matter where you are.
Does EveryDollar connect to my bank accounts for transaction tracking?
EveryDollar Plus, the premium version, offers bank connectivity to automatically import transactions, streamlining the budgeting process. The free version requires manual entry of transactions. This feature helps users keep track of their expenses more efficiently, reducing the time spent on manual data entry.
The Best Parts of EveryDollar: Budget Management
Things to Keep in Mind About EveryDollar: Budget Management